Laguna Beach Residences Seashore
photos on requestPrice on request
Phuket is a small island that behaves like several different ones. Each bay runs on its own rhythm, its own season and its own price per square metre, and the names buyers arrive with — Patong, Kata, Kamala — rarely map onto the life they actually want. Below is one table covering every district where we hold stock, plus the reasoning behind it: how many listings and developments, entry price, median, price per square metre, how many metres the district's projects sit from the sand, and who rents there. Island-wide that is 571 listings across 189 developments, from THB 2.1M, median THB 10.2M.
The numbers are live. They are recalculated from the same catalogue that feeds the property cards, so the two cannot drift apart: if a district empties out, its row disappears along with its prices. Beach distance comes from the project's own data sheet and is shown in metres, as a range across the district, from its closest project to its furthest.
You will not find drive times here — not to the airport, not to a school, not to a hospital. We have not measured them, and copying someone else's estimate into a table people use to commit seven figures is not a service. Phuket traffic in February and Phuket traffic in September are different roads.
Rows run north to south down the west coast, then the south coast, then the two inland districts with no sea frontage. Reading them in that order keeps neighbours side by side, which matters here: on Phuket the next bay along changes the price and the crowd far more than the distance between them suggests.
| District | Listings / developments | From, THB m | Median, THB m | Per m² | To the beach, m | Who rents here |
|---|---|---|---|---|---|---|
| Naithon | 16 / 5 | 3.2 | 38.7 | THB 106k/m² | 100–700 | Thin, seasonal demand; the bay keeps its own scale |
| Nai Yang | 33 / 10 | 2.1 | 6.9 | THB 125k/m² | 50–4,000 | Airline crews and frequent flyers; service demand, not tourist footfall |
| Layan | 59 / 14 | 3.5 | 12.3 | THB 148k/m² | 50–4,000 | Upper-bracket villas and residences, not a studio letting pool |
| Bang Tao | 186 / 69 | 3.1 | 12.3 | THB 140k/m² | 50–8,600 | Holidaymakers and long-stay winterers, year round; widest choice of formats |
| Surin | 24 / 4 | 4.5 | 7.9 | THB 170k/m² | 200–600 | Seasonal guests in beachside condos; evenings end early |
| Kamala | 42 / 12 | 4.0 | 11.3 | THB 135k/m² | 200–2,800 | Seasonal condo demand, November to April |
| Patong | 12 / 3 | 6.0 | 10.6 | THB 245k/m² | 100–6,000 | Nightly guests; the island's most reliable letting calendar |
| Karon | 22 / 9 | 4.1 | 6.6 | THB 137k/m² | 100–1,500 | Short-stay tourists through the high season |
| Kata | 16 / 3 | 3.2 | 6.6 | THB 144k/m² | 400–800 | Winterers and package tourists; the low season goes quiet |
| Nai Harn | 18 / 5 | 4.3 | 11.0 | THB 120k/m² | 750–2,200 | Long-stay residents and winterers on long contracts |
| Rawai | 53 / 19 | 3.6 | 8.0 | THB 142k/m² | 30–3,000 | Expatriates and winterers, monthly and annual leases |
| Chalong | 13 / 6 | 3.3 | 17.8 | THB 57k/m² | 800–9,200 | Expatriates on contracts, Muay Thai and dive crowds, boat owners |
| Thalang | 29 / 15 | 2.4 | 16.9 | THB 80k/m² | 2,000–10,000 | Year-round residents who want a house and land, not a nightly let |
| Kathu | 44 / 13 | 2.2 | 4.0 | THB 95k/m² | 1,100–11,400 | Island staff and school families, long leases |
Three things jump out of that table. A median does not rank a district: in Chalong and Thalang large villas push it up while the entry price sits below the island level. Kathu carries one of the lowest medians on Phuket for the mirror-image reason — there is no resort product in its catalogue at all. And Patong looks expensive not because the address commands a premium but because the cheap end of its stock has almost gone.
Prestige is the wrong axis. The working split is simpler: in one district the property finds its own guest for a week, in another your neighbour has lived on the same street for three years. The two run on different seasons and cost their owners different money, and the choice between them belongs before the viewing trip, not after it.
We are not going to talk you out of Patong. It delivers something no other district does: the Jungceylon complex with a full supermarket inside it, hundreds of kitchens on one walkable grid, gyms, a hospital and the sand itself, all without a car. If someone has told you to avoid Patong, understand who that advice was written for — a family buying a home, not a buyer after a rental asset or an urban seafront life.
What Patong does not have is worth knowing in advance. Villas and land for them ran out long ago, the building stock is dense and mostly not new, and the bottom of the market has thinned: the district median is THB 10.6M against THB 10.2M island-wide, with the catalogue starting at THB 6.0M. Quiet is not on the menu in either season.
The same island gets sold to three different people, and their objections are different too. Taking them one at a time saves a wasted viewing trip.
The north attracts the investor. The airport is close, there is still land, and construction is active — which produces the objections we hear on almost every viewing trip.
The west coast sells on a name someone already knows. It is also where "too commercialised" gets said most often — usually about a district the speaker last saw in February, at the top of the season, from a hotel.
The south is bought by people who intend to live on Phuket. School runs, a doctor, a gym and a market outweigh the view, and the airport stays at the other end of the island — a deliberate trade for quiet.
Four notable districts meet the sea differently from what a buyer expects, and on price per square metre they win more often than their reputation suggests.
For buyers whose family stays on another continent, the honest picture is short. Phuket has one international airport, operated by Airports of Thailand, in the north of the island, and it takes direct international flights — that part is the same wherever you buy. What the district changes is the drive at each end, and we do not publish that in minutes because we have not measured it. The practical reading: the northern districts sit nearest the terminal, the southern tip is the longest run on the island, and if you fly monthly that difference is worth more than a bay view.
Catalogue data ·
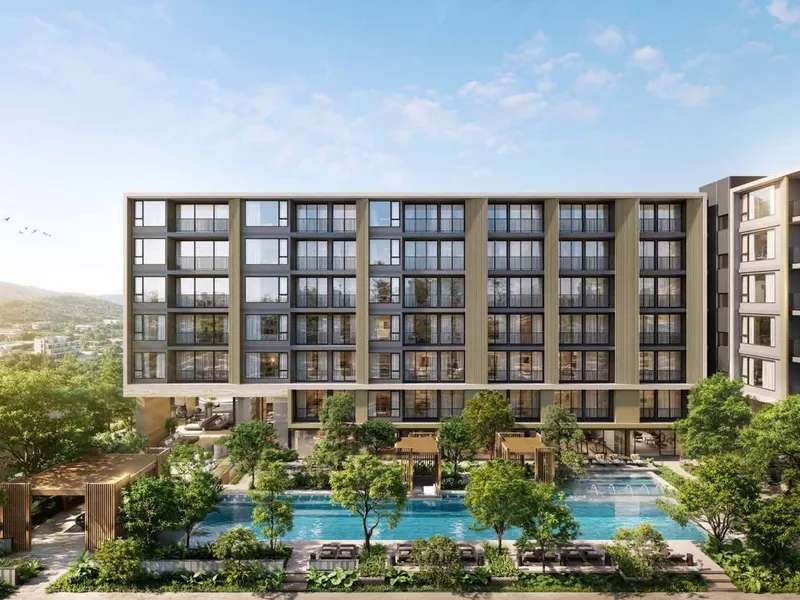 Developer render
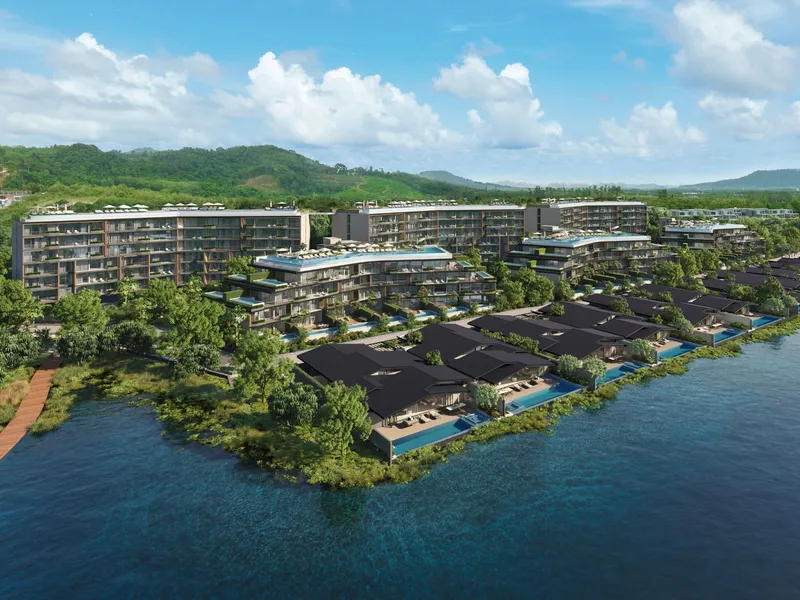 Developer render
We will send a pin, but for a specific project: a district is an area, not a point, and a marker in the middle of the bay explains nothing. In words, Chalong wraps around a large bay on the southeast coast. There is no swimming there — the water is shallow and the shore belongs to boats — but the district holds Phuket's main marina, Wat Chalong, and the roads toward Rawai, Nai Harn and Phuket Town. Current stock is 13 listings at a median of THB 17.8M.
Not necessarily. That advice is written for people buying a family home, and on those terms it holds: Patong is loud in both seasons, traffic is heavy, and villas barely exist there. If what you want is a mall, a gym and the beach within a short walk, or a unit that fills its own calendar, the same density is the reason to buy. The catalogue is almost entirely apartments, 12 of 12, starting at THB 6.0M with a median of THB 10.6M.
Patong first: the footfall is heavier than anywhere else on Phuket and it does not disappear in low season. Karon and Bang Tao run on the same logic with more space and, in Bang Tao's case, far more choice — 186 listings across 69 developments. Kamala works too, but its demand is openly seasonal, November to April. We do not promise a yield figure for any district: that number depends on the project, the management agreement and the season, and it has to be modelled on the unit you actually buy.
Look south and to the quiet northwest. Nai Harn is the most contained: 18 listings, low-rise, a beach with a lake behind it. Naithon is a single shorefront street between two headlands. Layan and Surin deliver quiet on the west coast, and Rawai offers a resident's routine instead of a resort one. The price of quiet is identical everywhere: a car is not optional, choice is narrow, and the right property is waited for.
It usually does, and it is worth settling before any deposit. A project data sheet gives a distance in metres to a named beach and nothing more: a road, a slope or a second row of buildings between you and the water never appears in that number. We read the distance next to the project map, and on a viewing we walk the route. The table above gives each district as a range, from its closest project to its furthest.
Depends what you are measuring. On entry price, Kathu (THB 2.2M) and Nai Yang (THB 2.1M) are the most accessible, and both carry low medians too. On price per square metre Kathu, Chalong and Thalang come out lower, because what you are buying there is floor area and a plot rather than a beachfront address. Entry price and median often disagree: Chalong and Thalang start below the island level while large villas drag their medians above it.
The inland and town-side districts, first of all: the international schools are not on the beaches. Kathu and Thalang put families closest to that infrastructure, and Chalong is the southern district families choose for the same reason. From Rawai or Nai Harn a school run is a real daily drive, which is a liveable trade for some households and not for others. Fix the specific school before the district, then price the route.
That is how a large part of the island already lives, and the pattern is always the same: home in one place, swimming in another. Rawai drives to Nai Harn and Yanui, Chalong to the southern bays, Kathu over the hill to Patong, Thalang west to Nai Yang and Naithon. The discount for that inconvenience is visible: Kathu's median is THB 4.0M against THB 10.2M island-wide. If walking to the water every morning is non-negotiable, buy the front row and budget accordingly.
We will answer your questions on this topic and send a shortlist of properties for your budget.